

 +86 15268683708


News




0102030405
Coffee and pepper grinders
Coffee Grinder Demand Trends in the US Market
2026-08-10
Coffee Grinder Demand Trends in the US Market
Table of Contents
- Understanding the US Coffee Grinder Market Foundation
- Core Drivers Fueling Sustained Market Growth
- Segmented Demand Breakdown: Grinder Types & Consumer Groups
- Retail Channel Preference Shifts Across the US
- Top Product Feature Trends American Buyers Prioritize
- Price Tier Performance & Profit Margin Opportunities
- Challenges Shaping Procurement & Product Development
- Future Demand Forecast for 2026–2035
- FAQs for Wholesale & Brand Procurement Partners
- Conclusion
Coffee culture has long been embedded into daily American life, and coffee grinders have evolved from niche specialty gear into a staple kitchen appliance across households, cafes, and retail assortments. For wholesale buyers, supermarket operators, and home appliance brand partners, mapping the shifting demand trends of US coffee grinders is critical to align inventory, product development, and category planning with real consumer behavior. This guide breaks down actionable market data, segmented buyer preferences, and long-term growth trajectories tailored for procurement and retail stakeholders.
Understanding the US Coffee Grinder Market Foundation
The United States holds 21.7% of the global coffee grinder market share, standing as the single largest national market for grinding equipment as of 2026. North America as a whole captures 38% of worldwide grinder revenue, with the US accounting for over 83% of regional sales volume.
Annual US domestic demand exceeds 6.8 million coffee grinder units sold in 2024, split across three core product categories: burr grinders (47% of unit sales), blade grinders (34%), and compact manual grinders (19%). Household consumption drives 44% of total purchases, while commercial coffee shops, restaurant chains, and office foodservice programs make up the remaining 56% of market volume.
National Coffee Association data confirms 66% of US adults drink coffee daily, the highest consumption rate recorded in two decades. For the first time in survey history, specialty coffee now surpasses traditional drip coffee in daily at-home consumption, directly lifting demand for precision grinding tools that unlock nuanced single-origin and craft brew flavors.
Core Drivers Fueling Sustained Market Growth
Four overlapping cultural and economic forces keep US coffee grinder demand expanding at a 5.7% compound annual growth rate through 2035.
1. The Rise of At-Home Specialty Coffee
Inflation has pushed average café coffee pricing up 23% over three years, encouraging households to replicate barista-quality drinks at home rather than purchasing daily takeaway beverages. 80% of Americans now prepare at least one cup of coffee in their residence each day, compared to just 8% who rely exclusively on shop-bought coffee. Freshly ground beans are widely recognized by US consumers as the single biggest upgrade to home coffee flavor, creating consistent replacement and new-unit purchase cycles.
2. Mainstream Adoption of Multi-Brew Methods
Pour-over, espresso, cold brew, and AeroPress brewing have moved beyond coffee enthusiast circles into mainstream suburban households. Each brewing technique requires a distinct grind size range, pushing buyers to seek grinders with adjustable precision settings rather than one-size-fits-all basic models. Retail surveys from Walmart and Target show grinders marketed as “multi-brew compatible” carry 32% higher sell-through rates than single-function budget grinders.
3. Growth of Outdoor & Portable Lifestyles
Camping, road tripping, office commuting, and outdoor tailgating culture across the US have created a fast-growing subsegment for compact, battery-powered manual and mini electric grinders. Social media content focused on outdoor coffee setups has accelerated consumer interest in lightweight, cordless grinding solutions, a category posting double-digit annual sales gains since 2023.
4. Specialty Café Network Expansion
Independent specialty coffee shops and regional chain locations continue opening nationwide, with each new location requiring commercial-grade burr grinders for daily service. Over 63% of US coffee shops upgrade their grinding equipment every 3–4 years to maintain consistent extraction quality, generating steady repeat bulk order demand from foodservice distributors.
Segmented Demand Breakdown: Grinder Types & Consumer Groups
Electric Burr Coffee Grinders (Highest Value Segment)
Burr grinders capture nearly half of all US grinder revenue, preferred by both serious home brewers and commercial foodservice buyers. Ceramic conical burr designs lead consumer preference because they generate minimal heat during grinding, preserving delicate coffee oils and flavor profiles— a selling point US retailers feature prominently in product signage and online listings. Flat steel burr variants dominate commercial wholesale orders, valued for fast high-volume grinding for espresso service.
Key buyer demographics:
- 25–39 year-old urban specialty coffee enthusiasts
- Mid-to-upscale independent coffee shops
- Premium home appliance brand assortments at Best Buy and Williams Sonoma
Budget Blade Electric Grinders (Mass Supermarket Staple)
Blade grinders retain 34% of unit sales volume, anchored by placement at Aldi, Walmart, and regional grocery chains targeting price-sensitive casual coffee drinkers. Most blade grinder buyers prioritize low upfront cost and compact countertop sizing over ultra-precise grind uniformity. Recent product upgrades focused on noise reduction and dishwasher-safe bowls have lifted repeat purchases in this low-margin, high-turn category.
Compact Manual Coffee Grinders (Fastest Growing Subcategory)
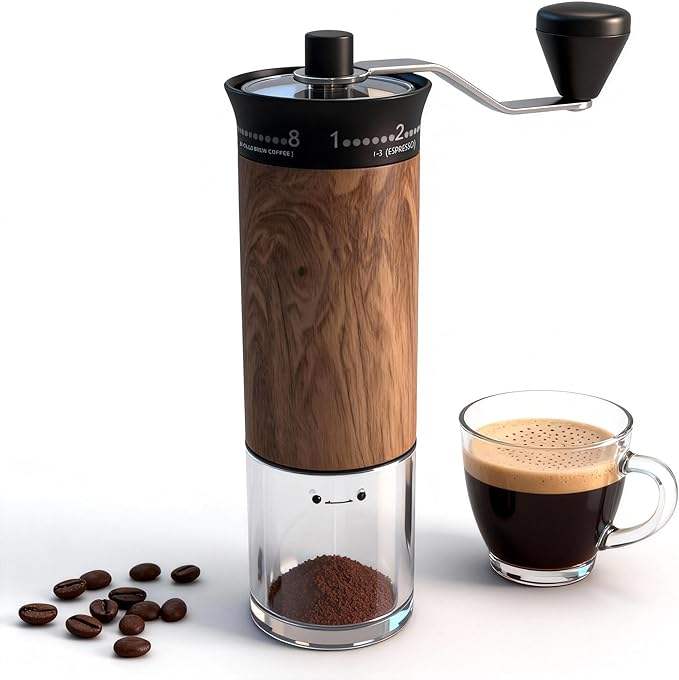
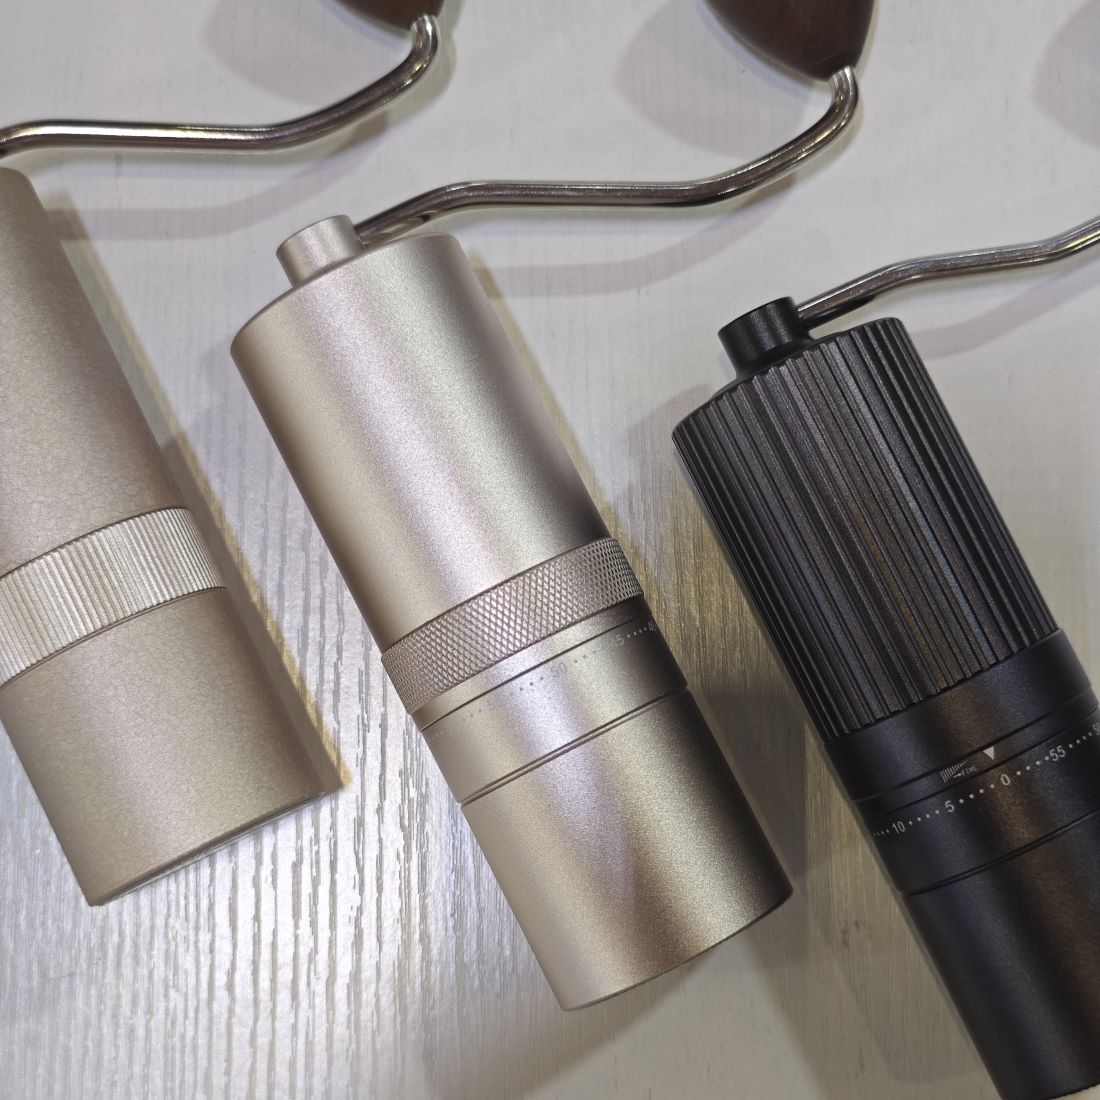
Manual stainless steel and wooden grinders represent the fastest-growing segment, driven by travel, outdoor recreation, and minimalist kitchen trends. These units account for 19% of total US grinder sales and grow at a 7.2% yearly clip, outpacing full-size electric models. Two distinct buyer groups fuel demand:
- Outdoor, camping, and travel consumers seeking cordless, lightweight gear
- Specialty coffee hobbyists who prefer low-heat hand grinding for pour-over and cold brew preparation
Retail Channel Preference Shifts Across the US
Distribution channel market share data from 2025 reveals clear procurement priorities for suppliers targeting US buyers:
-
Supermarkets & Big-Box Hypermarkets (38.75% market share) Walmart, Target, Aldi, and Kroger remain the largest physical retail outlet for coffee grinders, prioritizing mid-low price SKUs with high turnover and simplified packaging. Bulk seasonal ordering occurs in Q4 (holiday gifting) and Q2 (outdoor summer lifestyle sales). Retailers in this channel prioritize defect rates below 0.1% to avoid in-store returns and markdowns.


US Supermarket Retail Landscape
-
E-Commerce Marketplaces (Fastest Growing Channel, 11.98% CAGR) Amazon, Shopify DTC coffee brands, and specialty kitchen webstores capture expanding share, with portable and premium burr grinders performing best online. Cross-border e-commerce sellers demand small-batch customization (minimum order quantities starting at 500 units), private label logo printing, and FBA pre-labeling services to streamline US warehouse fulfillment.

Amazon US FBA Warehouse Operations
-
Specialty Kitchen & Coffee Retailers Independent coffee gear shops and premium home goods boutiques focus exclusively on high-margin burr and manual grinders, prioritizing exclusive colorways, premium material finishes, and regional underwriting distribution agreements to avoid price competition with mass retailers.
-
Commercial Foodservice Distributors Suppliers servicing cafes, hotels, and offices require heavy-duty commercial grinders with extended motor warranties, bulk spare parts kits, and compliance with US electrical safety standards (FCC certification mandatory for all electric units).
Top Product Feature Trends American Buyers Prioritize
US consumer product testing data and retail sales reports highlight non-negotiable features that lift conversion rates for all grinder categories:
1. Wide, Adjustable Grind Level Range
30+ grind settings are now baseline consumer expectation for multi-use electric burr grinders, covering ultra-fine espresso to coarse cold brew textures. Models with fewer than 20 settings see a 41% lower sell-through rate at mainstream retail. Ceramic conical burr mechanisms are heavily preferred over plastic alternatives for premium positioning.
2. Low Heat Grinding Technology
American specialty coffee buyers widely recognize heat as a flavor killer during grinding. Marketing copy emphasizing cold-grind ceramic burrs resonates strongly across all retail tiers, becoming a core differentiator between mid-tier and budget SKUs.
3. Compact, Space-Saving Footprints
Most US urban kitchens feature limited counter space, driving demand for slim-profile grinders, detachable grounds catch cups, and foldable manual crank designs. Portable rechargeable mini electric grinders with integrated carry handles perform exceptionally well in outdoor and e-commerce assortments.

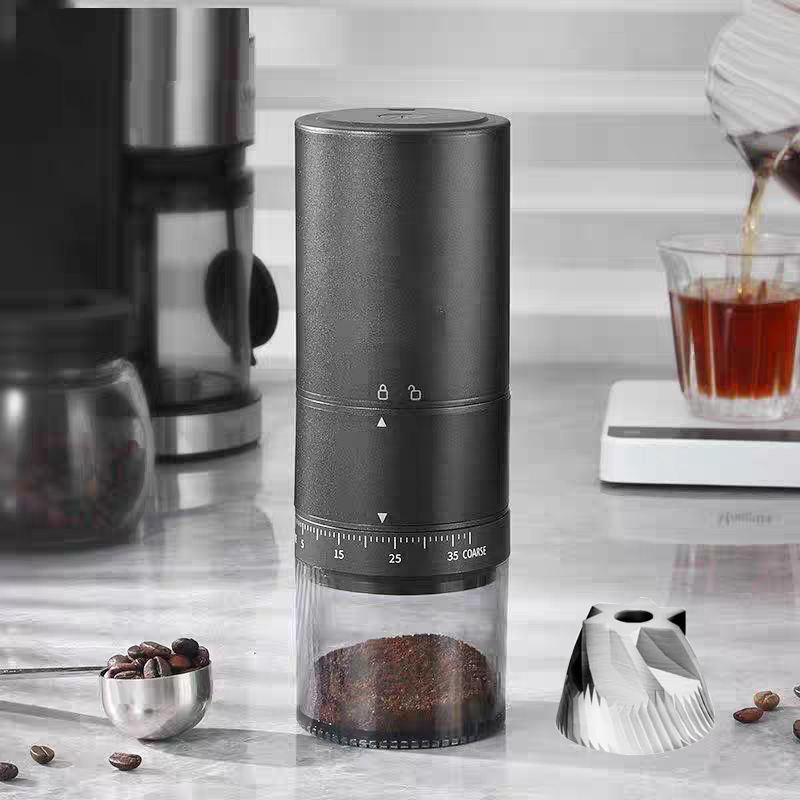
Electric Burr Coffee Grinder

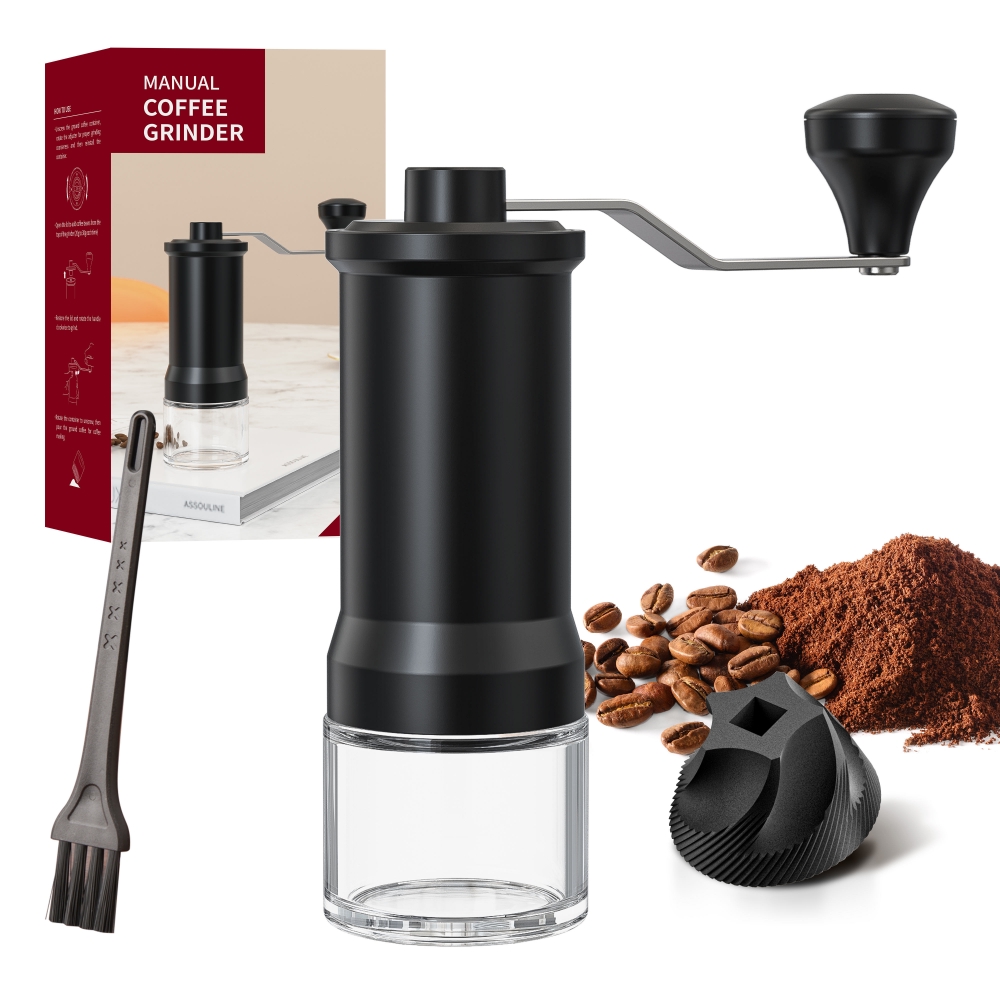
Portable Manual Coffee Grinder
4. Multi-Functional Versatility
Combination grinders compatible with coffee, pepper, and spices attract mass supermarket buyers seeking multi-use kitchen gadgets. All-in-one coffee-pepper grinder sets with matching wooden or stainless steel finishes rank among top holiday gift SKUs for US retailers.

Wood Pepper & Coffee Grinder Set
5. Compliance & Safety Certifications
Mandatory certifications for US market entry include FCC electrical safety, LFGB food-grade material approval for all contact surfaces, and RoHS compliance for internal electronics. Premium regional assortments additionally market Halal and SASO certification for ethnic consumer submarkets across Texas, California, and Florida.
Price Tier Performance & Profit Margin Opportunities
US retail pricing tiers demonstrate clear volume vs. margin tradeoffs that guide wholesale procurement strategies:
-
Entry Tier ($3–$15): Blade Grinders, Basic Manual Units Mass supermarket volume driver; high unit turnover, thin profit margins. Ideal for large batch 5-month cycle orders for national grocery chains. Food-grade ABS plastic construction is standard to hit price points while meeting safety standards.
-
Mid Tier ($16–$80): Standard Electric Burr, Premium Manual Grinders Balanced volume and profit, fastest overall retail growth segment. This tier targets mainstream specialty coffee households and DTC cross-border sellers, supporting customizable packaging and private label branding.
-
Premium Tier ($81–$300+): High-End Commercial & Home Burr Grinders Highest gross margin for brand partners and specialty retailers, lower unit volume. Buyers prioritize all-metal bodies, silent motor technology, digital grind adjustment panels, and regional exclusive distribution contracts.
Challenges Shaping Procurement & Product Development
Wholesale partners sourcing coffee grinders for the US market face three consistent industry headwinds that impact demand planning:
-
Raw Material Volatility Stainless steel and ceramic component cost fluctuations force frequent retail price adjustments, making consistent, long-term bulk supply partnerships valuable for stabilizing retail shelf pricing. Suppliers offering fixed-cost annual order contracts gain preference with large supermarket buyers.
-
Strict US Regulatory & Certification Rules All electric grinders sold domestically require full FCC testing and documentation; incomplete certification delays warehouse receiving and retail shelf placement by 4–8 weeks. Food contact materials must pass LFGB testing to avoid product recalls.
-
Competitive Private Label Saturation Amazon and mass retailers release in-house private label grinders at aggressive price points, squeezing margins for unbranded generic SKUs. Differentiated features (extra grind settings, unique exterior finishes, dual-purpose coffee/spice functionality) are required to stand out against store-brand competition.
Future Demand Forecast for 2026–2035
Market analysts project steady upward demand across every US coffee grinder segment through 2035, with key projected shifts:
- Total US household coffee grinder market value will reach $2.1 billion by 2033, growing at a 6.2% annual CAGR.
- Portable cordless mini electric and manual grinders will see the steepest growth, fueled by outdoor, travel, and office consumer trends.
- Sustainability will become a mandatory selling feature: recyclable packaging, biodegradable exterior plastics, and energy-efficient low-wattage motors will drive retail shelf placement priority by 2028.
- Smart connected grinder variants with app-programmable grind presets will capture 14% of premium electric burr sales by 2030, targeting tech-focused millennial and Gen Z coffee consumers.
- Commercial foodservice grinder demand will expand alongside specialty café openings in midwestern and southern US states, regions currently underserved by high-performance grinding equipment suppliers.
FAQs for Wholesale & Brand Procurement Partners
What grinder type delivers the highest retail turnover for US supermarkets?
Budget blade grinders lead unit volume sales, while mid-tier ceramic burr grinders deliver superior profit per unit. Supermarket buyers typically balance assortments with 60% entry blade SKUs, 30% mid burr models, and 10% portable manual grinders.
What minimum order quantities do US cross-border Amazon sellers require?
Most cross-border e-commerce buyers accept small-batch MOQs starting at 500 units, with add-on services including FBA labeling, customized printed boxes, and private logo engraving.
Which certifications are non-negotiable for selling grinders in the United States?
FCC electrical certification, RoHS electronic component compliance, and LFGB food-safe material testing are required for all consumer-facing grinders. Premium lines can add UKCA and Halal certifications to expand regional market reach.
How long is the typical bulk order lead time for US big-box retail?
Major supermarket chains operate on 5-month large-batch production cycles, with full four-stage quality control (raw material, semi-finished, production line, finished goods inspection) to maintain defect rates below 0.1%.
Are multi-purpose coffee + pepper grinder sets growing in US demand?
Yes. All-in-one grinding bundles rank among top holiday gifting SKUs, particularly wooden and stainless steel matched sets marketed toward home entertaining and outdoor barbecue consumer segments.
Conclusion
The US coffee grinder market maintains reliable long-term growth anchored by entrenched national coffee culture, the permanent shift toward at-home specialty brewing, and rising demand for portable, multi-functional kitchen appliances. For procurement, retail, and brand partners, successful category planning hinges on aligning product assortments with segmented buyer priorities: low-cost high-volume blade grinders for mass grocery, versatile ceramic burr models for mainstream specialty households, and compact manual/portable units to capture outdoor and travel-driven growth.
Moving forward, suppliers that prioritize standardized US safety certifications, customizable private label support, and sustainability-focused product upgrades will capture the largest share of expanding market demand across supermarket, e-commerce, and commercial foodservice channels nationwide.